YouTube

 Apple Podcasts

 Spotify

 iHeartRadio

 Podcast Addict

 Podchaser

 Deezer

 PlayerFM

 Castbox

 Goodpods

 RSS Feed

 Amazon Music
Powering AI Data Centers and Going Public via SPAC — Tod Higinbotham
ZincFive CEO Tod Higinbotham joins Mike Blankenship to explain why the nickel-zinc battery maker chose a SPAC over a traditional IPO, how the deal was built around a committed PIPE instead of the trust, and how AI and GPUs are transforming data center power.
Key Takeaways
- ZincFive chose a SPAC for valuation certainty and early committed capital, which a traditional IPO process could not guarantee up front.
- The deal was structured around a committed PIPE so it would not depend on trust dollars surviving redemptions.
- Investors are underwriting a growing backlog of contracted orders and improving margins, the revenue predictability many earlier SPAC companies lacked.
- Nickel-zinc batteries compete on power rather than energy, which suits short-duration data center backup.
- AI is driving higher power density, liquid cooling, GPU power transients, and a shift toward higher-voltage DC direct architectures.
ZincFive had real revenue and contracted orders it couldn't afford to turn down. So its CEO chose the path to public markets that offered certainty up front: a SPAC.
Tod Higinbotham, CEO and director of ZincFive, the Tualatin, Oregon-based maker of nickel-zinc batteries for data center backup power, joins host Mike Blankenship to explain why ZincFive pursued a business combination with Spark I Acquisition Corp. instead of a traditional IPO. Tod walks through why valuation certainty and committed capital mattered most, why the deal was built around a committed PIPE rather than the trust, and what investors are underwriting. He also breaks down how AI and GPUs are reshaping data center power, from liquid cooling to 800-volt DC architectures.
What We Cover:
- Why a revenue-stage company chose a de-SPAC over a traditional IPO
- Valuation certainty and committed capital as deal priorities
- Structuring a SPAC around a committed PIPE instead of trust dollars
- Planning for high redemption rates
- What investors underwrite: backlog visibility and margin progress
- Working capital in a growing manufacturing business
- Why nickel-zinc chemistry wins on power, not energy
- How GPUs and AI are changing data center power design
- GPU power transients and the move to higher voltage
- DC direct power and new battery markets
Connect with Tod Higinbotham
Website: zincfive.com
LinkedIn: linkedin.com/in/tod-higinbotham-20622542
Connect with Mike Blankenship
LinkedIn: linkedin.com/in/mikeblankenship
About Winston Taylor
Winston Taylor is an international law firm with a capital markets practice that works with companies and sponsors across the SPAC and public-company lifecycle. Learn more at winstontaylor.com.
Interested in joining a future episode? Reach out at thespacpodcast.com. The SPAC Podcast is part of One Iron Network. Explore the network at oneironnetwork.com.
Follow The SPAC Podcast
Website: thespacpodcast.com
LinkedIn: linkedin.com/company/thespacpodcast
YouTube: youtube.com/@thespacpodcast
A One Iron Network production: Executive Producer Joshua Wilson
Disclaimer: Michael J. Blankenship is a licensed attorney and partner at Winston Taylor. Joshua Wilson is a licensed Florida real estate broker and holds FINRA Series 79 and Series 63 licensure. The content of this podcast is for informational and educational purposes only and should not be considered legal, financial, or compliance advice. All views and opinions expressed by the hosts and guests are their own and do not necessarily reflect the policies or positions of any regulatory agency, law firm, organization, or employer. Listeners should consult their own legal counsel, compliance teams, or financial advisors to ensure adherence to applicable regulations, including SEC, FINRA, and other industry-specific requirements. This podcast does not constitute a solicitation or recommendation for any financial products or services.
Let's Connect on LinkedIn:
https://www.linkedin.com/in/mikeblankenship/ https://www.linkedin.com/in/joshuabrucewilson/
To Contact Us, Please Visit:
https://www.TheSPACPodcast.com/contact/
Frequently Asked Questions
Why did ZincFive choose a SPAC instead of a traditional IPO?
Tod Higinbotham says the SPAC route offered a valuation negotiated up front and the ability to secure committed capital early in the process. For a company that needed capital to fulfill contracted orders, that certainty mattered more than anything else.
How did ZincFive structure its SPAC deal around redemptions?
Rather than counting on money in the SPAC trust, ZincFive secured a committed PIPE early, so the transaction does not depend on trust funds remaining after redemptions. Any trust dollars that stay in are a bonus, not a requirement.
What are investors underwriting in the ZincFive de-SPAC?
According to Tod, investors are underwriting a growing backlog of contracted orders that is becoming more profitable: a traditional growth story built on predictable revenue.
What makes nickel-zinc batteries suited to data centers?
Nickel-zinc delivers high power over short durations, which fits UPS backup systems that cover anything from milliseconds to about five minutes. Tod notes that lithium remains the better fit for applications longer than an hour.
How is AI changing data center power?
GPUs have raised power density, pushed operators toward liquid cooling, and create sub-second power spikes when thousands of chips sync. The industry is responding with higher-voltage DC direct architectures.
00:00 - Welcome and Tod Higinbotham's Path to ZincFive
00:54 - What ZincFive Makes and the Nickel-Zinc Breakthrough
02:43 - Why a de-SPAC Instead of a Traditional IPO
05:58 - Structuring the Deal Around a Committed PIPE
08:05 - What Investors Are Being Asked to Underwrite
10:32 - Working Capital and the Manufacturing Model
12:48 - Why Nickel-Zinc Wins on Power
16:20 - How AI Is Changing Data Center Power
19:51 - Higher Voltage and GPU Power Transients
21:15 - A New Market for Pulse Power
23:11 - DC Direct and the 800-Volt Shift
24:04 - Wrap-Up
Mike Blankenship:
Mike Blankenship here with The SPAC Podcast. Today I'm joined by Tod Higinbotham. Tod, how are you doing today? Why don't you give us a few minutes about yourself?
Tod Higinbotham:
doing great, Mike. Thanks for having me. Yeah, so I I I didn't start off as a young child in the battery business or with a dream. I actually started more into semiconductor materials, advanced materials most of my career. worked for both public and private companies in that world. I was actually led into the battery world because of a a company called PowerGenix. It was a had a a big materials. IP portfolio. So that's what that that was sort of the common link for me and that's what that's what brought me here. So yeah, been with been with the company since the inception in twenty sixteen and you know we're we're about to go public.
Mike Blankenship:
Terrific. So I see the logo on your shirt there. So why don't you introduce ZincFive? Like what do you what do you make? who buys it and why does it matter right now?
Tod Higinbotham:
Yeah, absolutely. And since you pointed out the logo, so you know, when we when we named the company, we we focused on zinc because we make a nickel zinc battery. And the reason the zinc is important is because the nickel electrode is very similar to what people are commonly with nickel metal hydride or NiCad, nickel cadmium. So we're in that we're in that group or that family. And the breakthroughs in technology were were fundamentally around the zinc side and of course how to make the b the system work. But the company started off. we you know nickel zinc's been around since the time of Edison. so basically it was an Edison invention in the early 1900s and it was patented by Edison. So what we do today is very, very similar to that patent. but between that time and now the problem with nickel zinc was people just couldn't get it to cycle, it wouldn't last very long. It had great capability, but unfortunately very short life. and there were a few technical reasons for that. But the original founders of PowerGenix made a huge breakthrough in the chemistry. this is almost 20 years ago. and after that, they were able to stabilize the chemistry so they were able to make it work and build an entire portfolio of IP around that. You know, by the time they did that, people had sort of given up on nickel zinc. So when that happens, there's not a lot of patents and technology being done around a a battery that doesn't work. So that's the foundation of our company. and and basically f from there, you know, we we started to focus on applications that were good for our technology and and grew the company.
Mike Blankenship:
Terrific. Well, I understand you have real customers, real revenue. So you're not a pre-revenue company. so I guess that begs the question we're on The SPAC Podcast here. Why go through a de-SPAC instead of a traditional IPO or direct listing? Why why make that decision?
Tod Higinbotham:
Yeah, yeah, well I don't want to say it was thrust upon us, but you know, if you go back to when we entered the data center market, which is about six years ago, you know, batteries and and you know, capital intensive businesses need need a lot of capital. And we we looked at SPACs all along the way and you know I had come from a small cap public company, a Nasdaq company prior to this and From my standpoint, so it's gonna be difficult to be a public company when you really can't predict revenue and you know have a real firm plan for earnings and things like that. So we stayed away from it. And it it was hard then because some of our competitors were doing SPACs and getting big chunks of capital. And you know, you could have great technology, but if you don't have money, it does it doesn't really matter. So, you know, fast forward, you know, five years later, we found ourselves with a very Fast growing business. We've we finally broke into data centers and over about a four-year period, you know, grew our backlog to about $80 million. And what we were faced with is a popular technology gaining traction and POs that typically are sometime between six and twelve months before you ship them. So these are hard contracted POs and The last thing you want to do after a 10-year struggle, or in the case of the Edison technology, a hundred-year struggle, is to say no to POs. You know, it's just that's just not the way it works. So we looked at all the sources of capital and what we needed and how much. And we really came to the conclusion that SPAC was the perfect vehicle for us, mainly because the valuation certainty that we could get at the front end. So traditional IPO. It's tricky for a company like us, you know. We if we spend a year doing something and then if there's no certainty at the end, we're done. Right. You you just don't have the oxygen in in the form of cash to go that. So you need something certain. and so the the the feature of a SPAC of negotiating the valuation up front was really important. And then the ability to get committed capital at the beginning or early in the process. So those two things when you think about Whether it's an M&A transaction or an IPO, you know, you can spend months and months and months and lots of legal costs and banker costs, everything. At the end, nothing, zero. And and you know, we're w as I said, working for years and years and years to get POs from really good customers. The last thing they're gonna do is not deliver or even say no to POs because we've been fighting for them. So that's what led us to the SPAC. It was that sort of upfront valuation, certainty, and speed, you know, a bit faster, although you know, as the SPACs have matured and more more regulatory, more steps, more sophistication. You know, they do take longer than they used to, but they're still faster, than a traditional IPO, I believe, in in general.
Mike Blankenship:
Completely understand that. So you know, walk us through your structure here too much as much as you can here. So how how is the capital stack built and and how much are you depending on sort of the SPACs, the the trust?
Tod Higinbotham:
Yeah, so the capital structure is I I'll answer that question first. We're not. so when we got into the process of selecting a SPAC partner, you know, we just looked at the statistics on redemptions and most I mean a huge percentage of SPACs were a hundred percent. So, you know, it goes back to the certainty thing, which is unless that trust is certain, I can't count on it and I can't get to the end of the SPAC and have a hundred percent redemptions. Again, I'm dead. So basically the feature of ours was to get a PIPE committed up front very early in the process. So we have a hundred million dollar committed PIPE. and so that's the capital we're counting on. we do have s there is some money in trust, and if that comes, great. You know, that that that'll that'll be nice, that'll help us, but it's not needed. We built we built the entire transaction on certainty, and so the certainty of a PIPE, somewhat of a certainty of timing, although you know you have You have to get through SEC process and everything. But nevertheless, the certainty part of it. So $100 million. And we we sized that a couple of ways. One was we know we need to fund the growth of the business. And so we were thinking about that. And then we were also thinking about not needing additional capital get to get to EBITDA positive. So as you said, you know, we have you know. Five years of customers, growing backlog, real company. we started to break through to positive gross margins. So now all the investors are starting to look through, okay, we see that you've executed to that point. Now what is it gonna take to get to EBITDA? So we wanted to make sure the capital was sufficient to get us to that point. So that's how we sized it. That's why we did it the way we did it. and yeah, we're not really counting on trust dollars, but we'd we'd love to have them if they stay in.
Mike Blankenship:
Yeah, and it certainly validates the the valuation coming out, having the PIPE deal right there at the signing. So, you know, the the the SPAC cycle is marketed more, you know, more disciplined than it was maybe five years ago. you know, but the returns for some of the cohorts have been weak and you know, particularly seeing some of the battery related battery stock kind of falling off. What what are you asking investors or what you know, you did the PIPE, you've definitely talked to investors. What are you asking them to underwrite?
Tod Higinbotham:
Yeah, and and just to think think through that a little bit, going back to my story about our our SPAC journey, you know, in twenty you know, six years ago, we definitely could have done a SPAC. I think that the returns would have been shaky, right? Because the predictability of revenue. And so I think if you just think of all the universe of people had done a SPAC, the question is what's your predictability of revenue, your predictability of margins, those types of things. And so the returns the the lack of returns may have nothing to do with these the tech technology or their market position it's just was it predictable so so I think that's a a big part of for us we're really asking customers to come on the journey or the investors sorry not customers investors to come on the journey with us with our growing backlog so what we're telling them is you know we started this year With a backlog of about $81 million, 12/31, that was our published backlog. And then our most current public numbers, which are June of 2026, is 126.5. So that's what we're asking them to underwrite, which is a growing pipeline of orders that are becoming more and more profitable. So it it really is just the call it traditional growth story. and with that, you know, what investors want to hear is, you know. what's the sustainability of the story, what's the moat and the protection, you know, what's the strategy? But really the fundamental underlying is a is a growing backlog of certain business that the investors have their eye on. And so when we when we got our PIPE, you know, it was it was well before we had our Q one, Q2 pipe, you know, backlog. And so, you know, that was a I'm sure a big relief is to say, yep. You know, the the continued growth of that backlog is is looking strong. So that's the fundamental underwriting.
Mike Blankenship:
Yeah, and so what I'm hearing is sort of that capital that you're gonna have is is really funding that. And so what's that path to profitability for you once you've kind of funded all those orders?
Tod Higinbotham:
Yeah, well the funding itself, you're you're you're absolutely right, Mike. So we we we're heavy on working capital. So you know, we we actually manufacture the batteries from the chemistry, as you heard. Our IP is all around the chemistry. So we have two facilities in China and and we started in you know, we the company started in the US and the IP started here, but our manufacturing started up in China basically about eleven, twelve years ago, and we've scaled that up. So so basically we We we're a very light CapEx company, so just to give you the ratio there, we we build an economic size line for about thirty million dollars and that will produce approximately a hundred and fifty million dollars of annual revenue. So it's about a one-year payback, sort of at our our stated gross margin targets. So that's very attractive. S some of our competitors what I would say is we're much more like lead acid that way, we're low capex, and then you know lithium. Is about a one-to-one ratio, so 150 million to 150 million, because they use a lot more sophisticated equipment. You know, it's much more advanced technology, or we're using more traditional battery equipment. But 70-80% of our capital is poured back into inventory, right? It's this, it's this cash cycle to build the batteries in China, ship them to the US, build them into systems in the US or in Europe. We actually have an assembly facility in Europe as well. And it's funding that cash cycle. So some of the strategy moving forward will be, you know, how do we shorten that? And so like one of the ways is build the batteries closer to the customer, you know, eliminate a couple months of transition from ocean shipping and things like that. So yeah, basically 70% call it of the of the cap capex is is working capital for the growth that we continue to fund this this upscaling of the orders. And then capex for new capacity and also to say strategic capacity, bring things closer to customers.
Mike Blankenship:
So let's about the batteries themselves. So, you know, batter you know, why nickel zinc, you know, versus the lithium ion or some lead acid? Like what can it do that those other chemistries cannot do?
Tod Higinbotham:
Yeah, so Nickel Zinc's claim to fame has always been power. So for the the general viewer, you know, people use the terms energy and power interchangeably, but really when you think about batteries, what we're talking about is much shorter duration, less than one hour. So batteries are rated most typically kilowatt hours. You know, what's your energy per kilowatt hour, your cost per kilowatt hour? We don't do any hours. Our applications are far less than an hour. our core application where about 80-90% of our revenue comes from is from data center UPS, backup power. And the backup power system in data centers, basically the batteries are are are basically called is they're they're active on the bus, which which it means is with any short, short duration blip, the batteries will discharge. So make sure the servers don't reset. So you don't want to have any interruptions. And so Their spec to go up to five minutes. So that application is sort of from very, very short, you know, millisecond up to five minutes. And so the power rating is how fast it can discharge. So instead of an energy dense rating, you know, how much energy is in a specific space or specific weight, the challenge here is how fast can you get it out? Because the faster you can discharge, the actual less battery you need. As long as you have enough energy to get to five minutes. They don't need any more energy. So our competitors will typically have a lot of excess energy at the end of discharge because they're limited by the rate. They they have to add more batteries to get to the rate, which means we use less battery. So it becomes an economic benefit. And really, our batteries can be used. In fact, our first application, we were backing up traffic signals mostly in North America, and and we have thousands of these systems out there. That application is actually four hours to eight hours. A couple of states are eight hours, most of them are four, sort of governed by Department of Transportation codes and things. Our battery can do that. The problem is that we are would be larger and more expensive than a lithium battery for applications that are greater than an hour. So we just don't translate into that world. However, there are a few applications, traffic in one of them where lithium is is not allowed. And and and the reason is just it's a ultra safe called application. It doesn't maybe sound like it to people, but the batteries sit at the the intersection at the on the corner of the intersection in a traffic control box. And you know, because of congestion intersections and speed and light changes, that's where most accidents happen. And so the last thing you want to do is have two, three vehicles with fuel tanks or or EVs and then add a a flare of a battery at the corner. So so that's why. So I just bring that example up because we win on economics in power and then we can win on other things, safety, sustainability, other applications, but but not economics. So you'll never see us in a laptop, cell phone, EV, drone, so on and so forth. Anything mobile. Lithium, I I just don't see anything touching lithium.
Mike Blankenship:
Yeah. So AI is kind of driving you know, a large data center build out. You know, what's what's changing inside these facilities that, you know, creates the demand for for ZincFive and and how much that demand is real versus sort of expected.
Tod Higinbotham:
Yeah, yeah, the the simple answer what's changing is everything. So it's it's the most shocking thing I've ever seen in my history. And that is because when we entered the market, I would call the data center I would call it technology boring. And and the reason is just that it's a industry built off of scaling and reliability. So basically we're not looking for a lot of newfangled tech. What we're trying to do is execute efficiency. And so, you know, when you think about how the industry grew on one segment and that is the colo, these are all big real estate REITs and trusts and things building facilities and then leasing out the space, you know, leaving the shopping mall world and going to the data center world, a huge CapEx, you know, a a very straightforward amortization model. So when you come into that space with a new technology, you are not welcome. So all you're presenting is risk. So unless you really give a lever on something on those fundamental economics. So basically as we broke into the industry, that's what we were facing. It was very difficult. Fortunately, there was a change going on before AI, and that change was rapidly scaling power density driven by semiconductors. So basically chip scaling. For regular servers was causing higher power density, which means all the power infrastructure had to scale up. And that's right when we came in. So our model of we can go to higher power at a smaller footprint, we were met with a lot of we were we were welcomed because people were trying to do that. And when I say that, think of the people who sell the UPSs, our companies like Vertiv, Schneider, Eaton, Mitsubishi, Delta, sort of maybe the the biggest ones. Well, they've been They've been increasing the power density of their inverters. So, you know, what was traditionally call it a one-megawatt inverter in a space, that's up to 1.7, 1.8, even two. And some of them are introducing even larger ones. When I say larger, I mean capacity, not size, in the same footprint. And that's what's required. You know, so our batteries being able to do that, that really was a tailwind for us. But The introduction of GPUs and AI, it's changed everything. So now the power density and also how this how the chips actually interact with the power system has changed the ne the entire architecture's new. Everything is new. So you you've seen some of it, probably probably the one that's most public is liquid cooling. The power went up so high so fast we couldn't deal with the with the thermal load, so people have gone to liquid cooling. You know, big new market for liquid cooling. We actually play in that because the liquid cooling loops need their own backup. So we have a new backup market, which is just the liquid cooling loops. But more importantly, the industry, and particularly driven by the large hyperscalers, have looked at this and said, look, we need to increase voltage. We need to go up to higher medium to high voltage to deal with the to deal with the thermal load. So we w we have to drop the current. So the roadmap is now to go from what was nominally 48 volt for hyperscalers up to 800. 1000 1500. 800's been the sort of published, but I'm already hearing rumblings that that's not gonna do it. along with that, GPUs, because they're laid out with thousands of chips in a in an install, they sync. They they sync every second. So the to make a super compute mod you have thousands of chips working together, and when they do, they consume power in a dynamic fashion. There's a power transient spike. And that spike k i is is typical in a training mode, about 50 milliseconds, really short, but extremely high. About 50 plus percent over nominal. So a hundred megawatt data center is spiking every second to 150. And and and we and if you anybody knows anything about electrical grid, the grid doesn't like that. It's not looking for
Mike Blankenship:
Yeah.
Tod Higinbotham:
50% swings every second. So this became call it a problem. but For the people selling the GPUs, it's like it's not a problem, it's just a technical challenge to deal with because at that peak of that sync is when the the data throughput's the highest. This is a feature, not a bug of the GPU. So the entire industry has responded, and it goes back to the answer to my question. Everything has changed because we need to deal with power transients, we need to deal with high voltage, we need to deal with thermal loads. Right now the data centers laid out for the next two, three, four years don't look anything like the data centers of the past 30 years. So it became a technology-driven industry overnight, and we're still in recovery. Recovery can also be big opportunity. So for people like us with a differentiated technology. So the moral of the story is two year a year a year and a half ago, a couple of customers came to us and said, Can your batteries pulse? in meaning very short duration discharges. And we said yes, we had done some testing with the US military for pulsing application but this was very different those pulses were like six seconds this is fifty milliseconds so we have started building data sets around this our batteries are wonderful at this they this is what they could be made for the chemistry just lends itself to this because the shorter the duration the bigger our advantage with economics and the higher the pulse, the higher the power. It really eliminates a lot of the field because they're not power batteries or or high power devices like ours. So the markets actually come to us. It's a brand new market. So we now have a roadmap where we continue to advance our UPS, which is a rapidly growing business, and late next year we'll start introducing our dynamic load modules, which will be 800 volt and more. So right now we don't deal with that high volta higher voltage. so it's extremely exciting. And and you're I've long answered your question, but really that's what's happening in this industry. It is just completely changed. By the way, both trends I know I I identified driven by semic- semiconductor scaling, which is my former industry. So the advanced GPUs from NVIDIA and others, you know, those are coming from foundries like TSMC and they're able to Semiconductor scaling can move very quickly, usually quicker than most other industries can change. So it's really exciting what's happening right now and lots of opportunities, new partnerships. The other technical trend for those that are data center geeks listening is as you move to 800 volt, it's going to be DC direct. In the current colo data centers, it's 480 three-phase, typical industrial power. But it's double converted, so you know you have an inverter. So this is where the you know Vertivs and Schneiders come in. And it doesn't mean they're not playing in the new market or the old market's going away, but the new market is stated to be DC direct, means no inverter. And that is how the hyperscalers mostly do it today on their rack-mounted systems. They were already doing DC direct.
Mike Blankenship:
Well, Tod, this that is you you're super excited about it, which I love. And I I love hearing the science, even though, you know, as a lawyer, not playing
Tod Higinbotham:
Okay.
Mike Blankenship:
in the science. But we have a lot of clients in this area and it's certainly one that love to hear the success that you're having. and I really appreciate you coming on today to talk about ZincFive in the background and just the whole SPAC process that you're going through. So again, I appreciate
Tod Higinbotham:
Yeah, absolutely.
Mike Blankenship:
your time today.
Tod Higinbotham:
Yeah, absolutely. Thank you so much. And you know, I you know, even even finance guys like me and lawyers like you can get it, you know, so it's it's it's just power. So
Mike Blankenship:
True. I'll r I remember my elemental table there. So Zn.
Tod Higinbotham:
Exact exactly.
Mike Blankenship:
get it done. So again, thanks, Tod. That's so this is Mike with The SPAC Podcast.
Tod Higinbotham:
Right sounds good. Thank you.
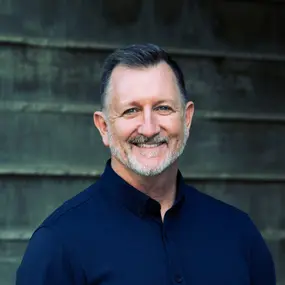
CEO, ZincFive
Tod Higinbotham is Chief Executive Officer and a director of ZincFive, a Tualatin, Oregon-based manufacturer of nickel-zinc batteries and battery-based power solutions for data center, industrial, and transportation applications. ZincFive has announced a business combination with Spark I Acquisition Corp. through which it intends to become a publicly traded company.
Before becoming CEO, Tod served as ZincFive's Chief Operating Officer from 2020 to 2025 and as President of its Battery Division from 2016 to 2020. Prior to ZincFive, he was CEO of PowerGenix, the company that pioneered the nickel-zinc battery technology at the core of ZincFive's product portfolio. Earlier in his career, he held roles of increasing responsibility at ATMI, a specialty materials company serving the semiconductor industry, ultimately serving as Executive Vice President and General Manager, and led sales and marketing at Advanced Silicon Materials, a producer of high-purity polysilicon and silane gas.
Tod holds an MBA from the University of Washington.